News dominating the week – a much-anticipated return to business for global oil flows amins the U.S./Iran war – caused yet another round of declines for two key benchmarks on Friday, as well as a third consecutive weekly decline as the latest round of Middle East hostilities failed to motivate traders.
As of 1709 GMT, Brent was down 61 cents at $91.37 per barrel; West Texas Intermediate eked out a 21-cent gain at $83.42 per barrel.
Brent is on track for a near 5 percent weekly decline and the December WTI contract for a 5.8 percent weekly drop; both benchmarks have fallen around 15 percent so far this month.
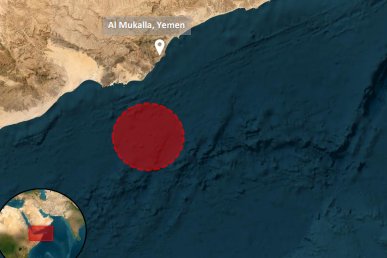
Iran-backed Houthis on Friday warned people near Saudi Arabia's Red Sea ports to evacuate and urged shipping companies to remove vessels, saying it would target ports in Jeddah and the Red Sea if a Saudi-led coalition struck Yemen's Hodeidah port.
This followed unverified claims by Iran's Revolutionary Guards navy that two oil tankers were burning after striking mines in the Strait of Hormuz.
But Phil Flynn, senior market analyst at Price Futures Group Inc., echoed the sentiment of the investment community by remarking, “It seems like that is somewhat priced into the market in this environment; there's weakness in the overall market."
Aldo Spanjer, commodity strategist at BNP Paribas, offered a contrary sentiment: "This week we keep having relatively strong export flows out of the Middle East; there is also a narrative ongoing that as long as people are talking, maybe there's a deal in the making.
"The prices are correct if you believe that this geopolitical risk doesn't come back [but] I'm not in that camp who thinks this is done ... I probably see a rebound."
For his part, Dennis Kissler, senior vice president for trading at BOK Financial Securities Inc., said, “While the near-term rise in geopolitical tensions is bringing some buying back to crude, the overall fundamentals are still moving more bearish,” and he pointed to Iraq selling physical crude at steep discounts.
The International Energy Agency held to its forecast of a 2 million barrel per day (bpd) surplus this quarter, and Goldman Sachs Group Inc. has warned of a glut risk in 2027.
In other war-related news on Friday, the South China Morning Post cited customs data showing that China’s crude imports from the Persian Gulf surged by 42.4 percent in October from September, to the highest level since the war began, thanks to Hormuz transits rebounding and Gulf producers slashing prices.
Also, media reported that Japan will purchase up to 8 million barrels of Saudi crude for the national petroleum reserve it depleted during the Hormuz blockage; the deal also gives Saudi Arabia temporary use of an additional 16 million barrels of storage capacity in Japan.