- Ship & Bunker raises G20-VLSFO Q4 forecast to $927/mt, from $882/mt in last month's outlook
- EIA lifts Q4 2026 Brent forecast to $109.13/bbl, up $4.44/bbl from October
- Full-year 2026 Brent forecast rises to $97.44/bbl from $96.32/bbl, 2027 to $85.78/bbl from $83.74/bbl
- Brent averaged $124/bbl in October as tanker attacks spread to the Black Sea and inventories continued to fall
- Current G20-VLSFO price stands at $844/mt, Singapore $816.50/mt, Rotterdam $703/mt
Ship & Bunker has raised its Q4 bunker price outlook for the third month in a row after the US Energy Information Administration (EIA) lifted its Q4 Brent crude forecast to $109/bbl in the November Short-Term Energy Outlook (STEO), published on Tuesday.
EIA now forecasts Brent to average $109.13/bbl in Q4 2026, up from $104.69/bbl in last month's outlook.
For the full year, EIA sees Brent averaging $97.44/bbl in 2026, up $1.12/bbl from the October STEO forecast of $96.32/bbl.
The 2027 profile is also higher.
While Q1 is unchanged at $94.90/bbl, Q2 rises to $89.00/bbl from $87.00/bbl, Q3 to $83.03/bbl from $80.03/bbl, and Q4 to $76.94/bbl from $73.94/bbl, taking the 2027 full-year forecast to $85.78/bbl from $83.74/bbl.
The spot price for Brent averaged $124/bbl in October, EIA said, $10/bbl higher than in September and well above the $104.69/bbl EIA had forecast for the quarter as a whole last month.
It was the highest monthly average since July 2022, when prices averaged $127/bbl adjusted for inflation, and the third consecutive monthly rise as global oil inventories continued to fall, EIA said.
Attacks on oil tankers continued around the Middle East and, more recently, in the Black Sea as a result of the conflict between Russia and Ukraine, further disrupting global oil flows and reducing the availability of tankers, which sent freight rates sharply higher, the agency noted.
Even so, Vortexa ship tracking data cited by EIA shows oil exports from the Middle East rose slightly in October following the restart of Saudi Arabia's East-West pipeline, while continued flows through the Strait of Hormuz using ship-to-ship transfers along Oman's coast added to supply.
That extra supply showed up in prices in late October and early November, with the Brent spot price falling below $100/bbl on November 4.
EIA estimates closure-related crude production shut-ins in the Middle East fell to 2.5 million b/d in October, down from 10.9 million b/d at the peak in May, and expects them to stay roughly flat through the rest of the year on the assumption that flows from the region remain somewhat constrained.
"Amid ongoing constraints, we forecast Brent will average around $100/b during November and December," EIA said in the report.
Global oil inventories fell by an estimated 1.2 million b/d in Q3 but should start building in Q4, although EIA says the heightened risk of supply disruptions and longer shipping routes will limit the near-term effect of those builds on prices.
The agency expects inventories to build by 3.5 million b/d in the first half of 2027, pushing Brent below $90/bbl in Q2, with most Middle East production outside Iran back at pre-conflict levels by the end of that quarter and prices easing to an average of $77/bbl in Q4 2027.
Iranian exports are expected to remain constrained throughout the forecast period, and EIA warns that crude flows from the region, through Hormuz and the bypass routes alike, will remain susceptible to disruption, with more short-term volatility than its monthly forecast shows.
The forecast was finalised on November 5 and does not account for market events after that date, EIA said.
Bunker Price Implications
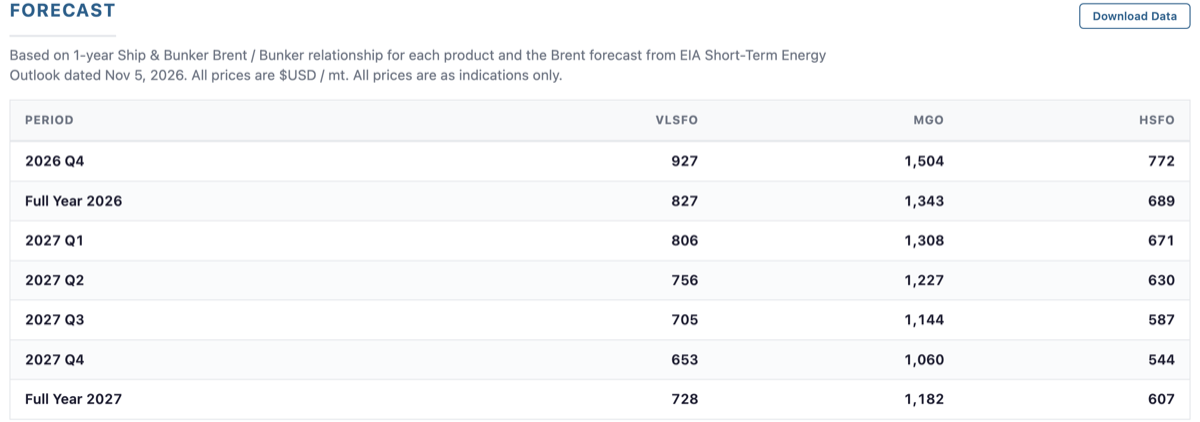
Based on EIA's updated crude outlook, Ship & Bunker now forecasts VLSFO prices at primary bunkering ports, as tracked by the G20-VLSFO Index, to average $927/mt in Q4 2026, up from $882/mt in last month's outlook.
For the full year, the revised EIA forecast implies a G20-VLSFO average of $827/mt in 2026 and $728/mt in 2027, compared with $811/mt and $705/mt in the October outlook.
The G20-HSFO Index is now forecast to average $772/mt in Q4 and $689/mt for full year 2026, up from $735/mt and $676/mt respectively last month, while the G20-MGO Index is forecast at $1,504/mt in Q4 and $1,343/mt for the full year, up from $1,418/mt and $1,305/mt.
Current G20-VLSFO prices stand at $844/mt, with VLSFO prices at $816.50/mt in Singapore and $703/mt in Rotterdam.
In Singapore, the world's largest marine fuel hub by sales volume, Ship & Bunker forecasts VLSFO to average $893/mt in Q4, $798/mt for full year 2026, and $702/mt for 2027, up from $842/mt, $775/mt, and $674/mt respectively in the October outlook.
At the key European hub of Rotterdam, the Q4 VLSFO forecast is $776/mt, with $693/mt for full year 2026 and $610/mt for 2027, compared with $743/mt, $683/mt, and $594/mt last month.
Ship & Bunker publishes bunker price forecasts for every port and index it covers, based on the Brent forecasts from the monthly EIA STEO.
The forecasts are based on the average price relationship between each fuel and Brent over the previous 12 months.